$325,000 Recovered After a Red-Light Collision in Gulf Shores, Alabama
Publish Date : 02 November 2026
Note: We have changed our client’s name in this case study to protect her privacy.
Louise was driving through a Gulf Shores intersection on a green light when an eighteen-year-old driver ran the red light at roughly 56 mph and struck her directly in the driver’s door, trapping her inside until Fire and EMS crews removed the door to get her out. Imaging revealed a displaced, comminuted fracture of the left femoral neck along with fractures of the hip socket, pubic bone, and sacrum. Because the at-fault driver carried only $25,000 in liability coverage, securing meaningful compensation required pursuing Louise’s own underinsured motorist coverage, bringing her total recovery to $325,000.
 40+ years of combined legal experience
 Free & confidential case evaluations
 Home or hospital visits available
Proven Results
Our Record-Setting Verdicts and Settlements
$10M+
Civil Litigation
Settlement involving civil litigation in Alabama
$10M+
Personal Injury
Settlement involving a workplace injury
$8M+
Medical Malpractice
Jury verdict in medical malpractice against OB/GYN in wrongful death of an infant
From $25,000 in Liability Coverage to a $325,000 Recovery
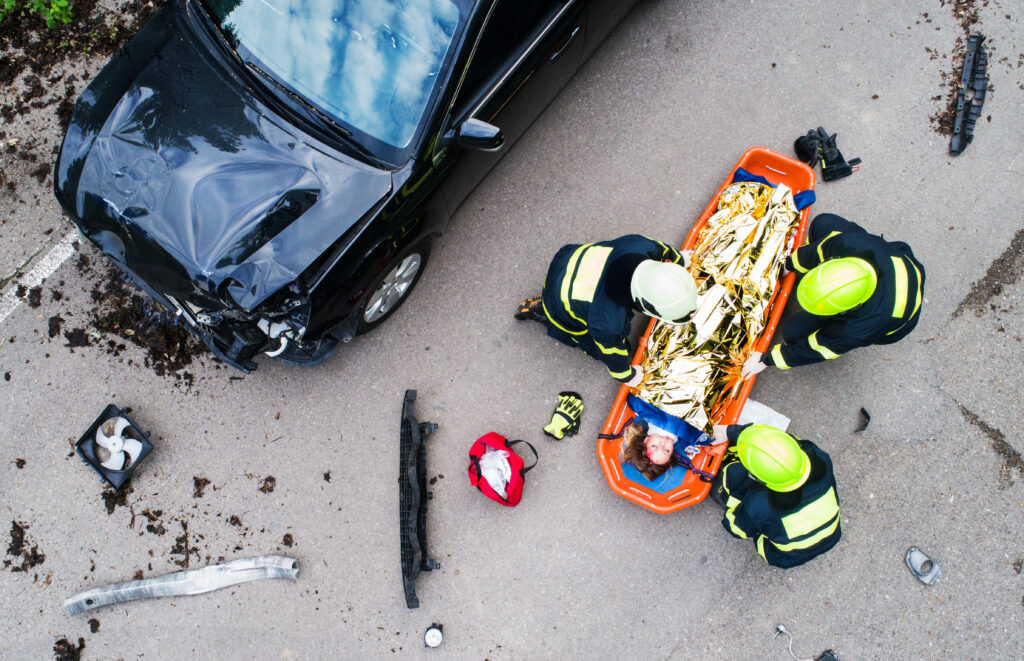
In September 2024, Louise entered the intersection of Highway 59 and West 36th Avenue in Gulf Shores on a green light.
The other driver was traveling north on Highway 59 at an estimated 56 mph in a 45 mph zone when she ran the red light and struck Louise’s vehicle broadside in the driver’s door.
The crash report attributed the collision to the other driver, who was cited at the scene. Liability was never seriously disputed.
The problem was insurance coverage. The at-fault driver had only $25,000 in liability limits, an amount that could not come close to accounting for Louise’s injuries. The remainder of the recovery had to be pursued through Louise’s own underinsured motorist coverage.
Her total recovery was ultimately $325,000.
How the Gulf Shores Red-Light Collision Happened
Louise was proceeding through the signalized intersection on a green light when the other driver entered against the red signal.
The side impact struck Louise directly at the driver’s door. She was trapped inside the vehicle, and emergency crews had to remove the door before they could get her out.
Louise was transported by ambulance to a regional medical center and transferred that same night to a higher level of care under an accepting orthopedic physician.
The Alabama Uniform Traffic Crash Report identified the red-light violation as the contributing circumstance, and the other driver was cited at the scene.
Louise’s Hip and Pelvic Fractures
CT imaging documented several serious acute injuries.
Louise suffered a displaced, comminuted fracture of the left femoral neck, the portion of the thigh bone connecting to the hip. She also sustained a fracture through the front wall of the left hip socket, a nondisplaced fracture of the left pubic bone, and a minimally displaced fracture of the left sacrum.
She also had a seatbelt-related contusion across the abdominal wall.
Louise was stabilized with pain management, IV fluids, and diagnostic imaging before being transferred to another facility for orthopedic treatment.

The Coverage Problem: The At-Fault Driver Had Only $25,000
The crash report attributed the collision to the other driver running the red light, the driver was cited at the scene, and nothing in the available record suggests Louise contributed to the crash.
Within roughly two months of the collision, the other driver’s insurer tendered its full $25,000 liability policy limit.
That was not an assessment of the full value of Louise’s injuries. It was simply all the at-fault driver’s policy could provide.
The case therefore shifted to Louise’s own underinsured motorist coverage. Her UIM carrier became a defendant in the lawsuit, opening another source of recovery beyond the at-fault driver’s limited policy.
Attorney Randall Caldwell explained the coverage problem:
The driver who hit her had a twenty-five-thousand-dollar policy. Our client had a shattered hip and a car door that had to be cut off to get her out of it. Twenty-five thousand dollars was the whole world as far as that driver’s insurance was concerned, and it was not close to enough. The only place the rest of it was ever going to come from was our client’s own underinsured motorist coverage, which is the coverage most people are paying for and do not know they have until a day like that one.
Settling the case and getting paid turned out to be two different projects. We had an agreement for the liability limits, and they would not finalize it over paperwork the law does not require anybody to produce. At some point you stop writing letters and you file the motion.
C. Randall Caldwell, Jr.
How the Evidence Supported the UIM Claim
There was no need for an accident reconstruction. The crash report and citation established a strong liability record from the beginning.
The medical evidence was equally objective. CT imaging documented multiple acute fractures, while the emergency response itself showed the force of the collision: Louise was trapped inside the vehicle and rescuers had to remove the driver’s door to reach her.
Those facts shifted the focus away from proving who caused the collision and toward identifying enough insurance coverage to address the severity of the loss.
How the Claim Grew From $25,000 to $325,000
The at-fault driver’s insurer tendered its full $25,000 liability limits on November 6, 2024, shortly after the firm became involved.
Rather than treating those policy limits as the end of the claim, the case continued against Louise’s own underinsured motorist carrier.
That UIM claim ultimately resolved for $300,000 in September 2025.
Combined with the at-fault driver’s $25,000 liability limits, Louise’s total recovery reached $325,000, thirteen times the amount available from the other driver’s insurance alone.
When an Agreed $25,000 Payment Still Had to Be Enforced
Resolving the UIM claim did not completely end the case.
After the $300,000 UIM settlement was reached, the at-fault driver’s side still did not finalize the previously agreed $25,000 liability payment. The dispute centered on subrogation information that had not been made part of the settlement.
The firm filed a Motion to Enforce Settlement Agreement, or alternatively to return the case to the trial track.
The motion made clear that if the defense denied an enforceable settlement existed, Louise was prepared to withdraw the settlement offers and pursue a verdict beyond the policy limits.
The signed disbursement statement later confirmed the full $325,000 recovery.
The Result: $325,000 Recovered From Two Sources of Insurance
Louise recovered $325,000 in total:
- $25,000 from the at-fault driver’s liability coverage
- $300,000 through her own underinsured motorist coverage
The firm also resolved $54,144.93 in outstanding medical obligations.
The largest health insurance subrogation claim was reduced by $25,935.41, resulting in a final payment of $51,880.00. Other outstanding ambulance, anesthesia, physical therapy, and emergency facility balances were also resolved.
After fees, expenses, and outstanding medical obligations, Louise’s net recovery was $155,182.74.
The client signed the final disbursement statement in March 2026.
What This Case Says About Our Approach
Louise’s case shows why the value of an injury claim and the amount of insurance carried by the person who caused it are two very different things.
Policy limits are a starting point, not necessarily the end of the claim.
A $25,000 liability policy did not define the value of injuries this serious.
Coverage analysis can be just as important as liability analysis.
Recognizing the UIM claim early opened a path to recovery that was twelve times larger than the other driver’s policy alone.
Strong evidence lets the case focus on the real obstacle.
With fault well documented, attention could stay on damages, coverage, and collection rather than an unnecessary liability fight.
A settlement is not finished until the money is actually paid.
When the liability payment stalled after an agreement had been reached, returning to court became part of protecting the result.
What the client keeps matters too.
Reducing the largest medical lien by more than $25,000 increased the portion of the recovery available after outstanding obligations were resolved.
This case required more than proving who ran the red light. It required finding the coverage capable of responding to a serious injury and continuing the work until the agreed recovery was actually secured.


Explore Our Other Case Studies
Caldwell Wenzel and Asthana Personal Injury Lawyers represents injury victims across Alabama, Mississippi, and Florida. Explore our other case studies to see how we’ve handled serious injuries, insurance coverage issues, and cases requiring litigation.
$650,000
Recovery After a Disputed-Liability Motorcycle Crash in Gulf Shores
A crash report blamed our client after a motorcycle collision left him with catastrophic leg, foot, and hand injuries. We challenged the liability evidence and secured a $650,000 recovery.
Read case study$400,000
Settlement After a Commercial Driver Turned Left Across Our Client’s Path
A company driver failed to yield, leaving our client with neck fractures, a vertebral artery injury, and eventual cervical fusion. We secured a $400,000 settlement.
Read case studyTalk to Caldwell Wenzel and Asthana Personal Injury Lawyers About Your Case
If the driver who caused your accident does not have enough insurance to cover your injuries, your own policy may provide additional protection. Our Alabama car accident attorneys can review the available liability and underinsured motorist coverage and explain your options.